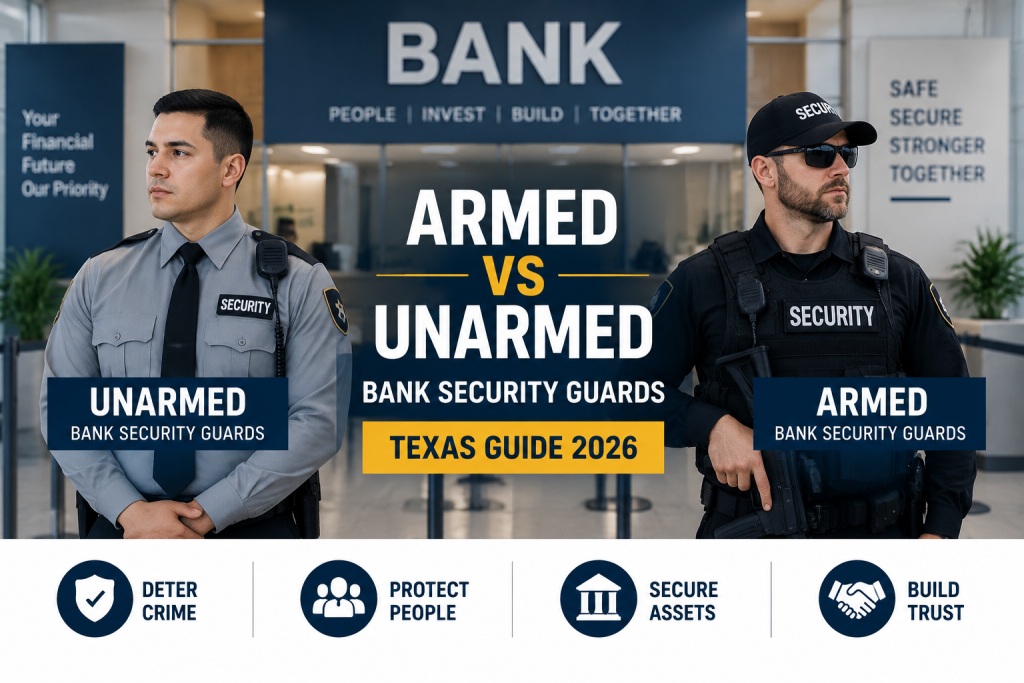
For board members, chief risk officers, and facility directors managing commercial banks, credit unions, and wealth management centers across Greater Houston and Texas, deciding between armed and unarmed bank security guards is among the most consequential operational risk choices. Unlike retail strip centers or construction compounds, financial institutions manage dense liquid assets, face strict federal regulatory mandates, and serve daily consumer traffic within compact, enclosed interior spaces.
Under the federal statutory framework of the Bank Protection Act guidelines, institutions must assess whether their specific geographic exposure, transaction volume, and emergency response parameters require enhanced physical deterrence. However, deploying armed personnel inside a bank branch introduces unique considerations: customer comfort, firearm retention liabilities, crossfire hazards in lobby settings, and strict state licensing compliance.
Conversely, relying solely on unarmed staff in high-crime metropolitan corridors leaves tellers, vault staff, and patrons vulnerable to takeover robberies that unarmed guards cannot counter. This comprehensive decision matrix analyzes operational differences, liability equations, regulatory guidelines, and Texas Department of Public Safety (DPS) licensing standards to help financial executives select the right guard force. If you are evaluating providers of professional bank security guard services in Houston, this guide gives you the framework to brief them.
Phase 1: Operational Comparison: Armed vs Unarmed in Banking
The operational divide between armed and unarmed bank security officers involves weapon carry, tactical utility, and psychological deterrence across daily branch operations:
| Operational Dimension | Unarmed Officers (Texas DPS Level II) | Armed Officers (Texas DPS Level III Commissioned) |
|---|---|---|
| Primary Mission Profile | Customer service presence, lobby queue management, visual observation, and access compliance. | Violent crime deterrence, active robbery defense, vault transfer escort, and rapid threat neutralization. |
| Deterrence Capability | Deters low-level opportunistic trespassers, panhandlers, and unruly customers; minimal deterrence against armed syndicates. | High-impact psychological deterrence against planned armed robberies and organized vehicle smash-and-grabs. |
| Response to Armed Threat | Observe and report; trigger silent duress alarms; assist staff with evacuation and police coordination. | Tactical engagement, physical interception, weapon deployment under lethal force guidelines, and suspect containment. |
| ATM & Cash Transfer Security | Performs visual checks for skimmers; see physical inspections in our ATM skimming detection guide. | Provides armed physical security perimeter during technician servicing, cash replenishment, and night-drop collection. |
| Average Texas Hourly Rate | 22 to 32 dollars / hour | 34 to 48 dollars / hour |
For complete baseline rate calculations and shift budget models across commercial environments, examine our detailed resource on security officer hourly costs in Houston.
Phase 2: The Armed Officer (Texas DPS Level III): Advantages and Liability Risks
Commissioned armed officers provide robust physical deterrence for bank branches, but their deployment requires clear operational oversight:
1. High-Impact Deterrence Against Organized Bank Crews
Bank robbery crews conduct pre-attack reconnaissance to evaluate potential resistance. An alert, professional armed officer stationed near the entrance or visible through glass lobbies alters risk-reward calculations. Criminals seeking quick access typically redirect toward unstaffed branches or standalone kiosks. This is the single strongest argument for hiring armed security guards for banks in higher-risk corridors.
2. Active Defense During Cash Transit Windows
Opening and closing hours, along with armored carrier cash deliveries, carry elevated robbery risk. Armed officers establish a tactical security perimeter, monitor approach corridors, and escort staff during vault cycling and cash transit; explore opening routines in our manual on opening and closing security protocols for bank branches.
3. The Critical Liability Profile: Weapon Retention and Crossfire Hazards
Deploying armed personnel introduces distinct operational liabilities:
- Firearm Retention Scenarios: In a crowded banking lobby, an officer in close proximity to visitors risks an attempted firearm grab by a hostile individual. Armed officers must use Level III retention holsters and undergo rigorous weapon-retention training.
- Bystander Crossfire and Ballistic Penetration: A firearm discharge inside a bank branch involves glass partitions, concrete pillars, and crowded teller queues. Errant rounds carry catastrophic civil liability. Officers must be trained in target backdrop discipline and shoot/don’t-shoot judgment.
- Insurance Riders: Carrying armed officers requires dedicated armed liability coverage riders, which increase guard company billing rates.
Before contracting any bank security guard company, review our structured security vendor evaluation checklist to verify active Texas DPS firearms certifications and adequate commercial general liability coverage.
Phase 3: The Unarmed Officer (Texas DPS Level II): Role and Tactical Limits
Unarmed officers remain common across community banking and credit union environments, offering key advantages alongside definite operational boundaries:
1. Approachable Customer Ambience
In private wealth advisory offices and community credit unions, visible firearms can make patrons uneasy. Unarmed officers provide a welcoming customer-service presence while maintaining lobby vigilance; evaluate service roles in our analysis of concierge vs dedicated security guard models.
2. De-Escalation of Non-Violent Disputes
Most daily branch disruptions involve contested checks, account freezes, or agitated patrons rather than armed robberies. Unarmed guards trained in verbal de-escalation resolve disputes without introducing a firearm into the interaction.
3. Reduced Institutional Civil Liability
Because unarmed guards do not carry lethal weapons, institutions eliminate exposure to firearm discharge lawsuits, accidental weapon discharges, or excessive force litigation tied to firearms.
4. Limited Tactical Capability
If an armed robbery or violent takeover occurs, an unarmed guard cannot physically engage the assailant. Their operational protocol is limited to seeking cover, triggering silent duress alarms, and observing suspect details.
To examine how human guard staffing compares directly against electronic surveillance and camera systems, explore our operational report on security guards vs surveillance cameras for commercial facilities.
Phase 4: Decision Framework: Choosing the Right Guard Force for Your Branch
When evaluating security for banks, financial institution risk managers should measure their branch footprint against five core risk variables:
1. Evaluate Municipal Crime Analytics
Under federal Bank Protection Act mandates, institutions must document regional crime trends. If the branch ZIP code exhibits elevated commercial robbery rates, ATM tampering, or armed gang activity, deploying Texas DPS Level III commissioned armed officers is an essential risk control.
2. Analyze Cash Volume and Vault Complexity
Branches functioning as regional cash hubs – holding extensive on-site vault reserves, processing high-volume merchant deposits, or coordinating frequent armored carrier transfers – require armed security. Branches with limited on-site cash reserves or automated cash recyclers (TCRs) can safely operate with unarmed personnel.
3. Physical Architecture and Sightlines
Standalone pad sites with open glass envelopes, multiple entry vestibules, and isolated drive-thru lanes present vulnerable tactical sightlines. Armed officers provide perimeter monitoring and deter external ambushes; review ingress security principles in our guide on access control best practices for commercial facilities.
4. Emergency Response Proximity
If local municipal police dispatch averages response times under three minutes, unarmed guards supported by silent duress buttons may suffice. For suburban or rural branches where law enforcement arrival takes 10 to 20 minutes, armed personnel provide immediate on-site defense.
5. Customer Demographics and Brand Perception
Guard force selection is also a brand decision. A downtown Houston commercial branch serving corporate treasury clients may expect visible armed deterrence, while a suburban credit union serving families may prefer an unarmed, hospitality-forward presence. The correct bank security services partner tailors uniform standards, weapon posture, and demeanor to the branch’s specific clientele rather than applying a single template across the network.
Phase 5: Texas Regulatory Standards and DPS Guard Licensing
Deploying bank security guards across Texas requires strict adherence to Chapter 1702 of the Texas Occupations Code:
1. Texas DPS Level II (Non-Commissioned) vs Level III (Commissioned)
Non-commissioned Level II guards complete mandatory state criminal history background checks and core regulatory training, but cannot carry weapons. Commissioned Level III officers must complete a rigorous 45-hour training curriculum covering defensive tactics, Texas Penal Code use-of-force statutes, intermediate weapon operation, and state-mandated firearms qualification with specific handguns and calibers.
2. Contractor Licensing Verification
Banks must confirm that their security guard services for banks vendor maintains an active Class B (Security Contractor) or Class C (Combination) license issued by the Texas DPS Private Security Bureau. Utilizing unlicensed guard services or informal off-payroll staff exposes the financial institution to severe regulatory sanctions and invalidates standard commercial insurance protections.
For executive bank leadership, board members, or high-net-worth wealth clients facing specific external threats or personal safety concerns, examine our diagnostic manual on 7 signs you need a personal security detail.
Bank Security Guards in Houston: Local Deployment Considerations
Houston’s financial footprint spans dense downtown corporate towers, Galleria-area wealth management offices, Energy Corridor commercial branches, and suburban credit unions across Harris, Fort Bend, and Montgomery Counties. Each environment carries a different threat profile, so a one-size-fits-all guard force rarely fits a multi-branch network.
A qualified Houston bank security guard company should be able to blend armed Level III officers at high-cash regional hubs with unarmed Level II officers at lower-risk retail branches, all under a single supervised, insured contract. Whether you need a single lobby bank guard or a fully staffed multi-branch program, matching officer tier to branch risk is what keeps both compliance and budget intact. Explore the full scope of our commercial security services for financial institutions across Greater Houston.
Partner with Gods Armour Security for Financial Institution Protection
Safeguarding bank branches, credit unions, commercial vaults, and financial headquarters requires a dependable physical security partner. Gods Armour Security provides Texas DPS certified security officers, Level III commissioned armed guards, and mobile patrol response units tailored to the operational and compliance standards of Texas financial institutions.
Our supervisory leadership collaborates directly with bank security officers and branch managers across Greater Houston, Harris County, and statewide Texas to evaluate vulnerability profiles, implement access control protocols, safeguard cash handling windows, and maintain full regulatory compliance.
Need a customized evaluation of bank security guard services in Houston for your branch network? Request a bank security consultation and risk assessment or contact our Houston command operations desk directly at (713) 878-9984.
Frequently Asked Questions
Do banks have armed guards?
Many banks do, but it is not universally required by federal law. The Bank Protection Act mandates a written security program and baseline devices, then leaves the armed-versus-unarmed decision to each institution’s documented risk assessment. High-cash regional hubs and branches in higher-crime corridors commonly deploy armed Texas DPS Level III officers, while lower-risk community branches often use unarmed Level II guards.
Are bank security guards armed or unarmed?
Both models are used. Unarmed Level II officers focus on customer service, access control, and observe-and-report duties. Armed Level III commissioned officers add active robbery deterrence and secure cash-transit windows. The right choice depends on local crime rates, on-site cash volume, branch layout, and police response times.
How much do bank security guards cost in Texas?
Unarmed Level II bank security officers in Texas typically bill at roughly 22 to 32 dollars per hour, while armed Level III commissioned officers range from about 34 to 48 dollars per hour. Armed coverage costs more because of firearms qualification, retention training, and dedicated armed liability insurance riders.
Do credit unions need armed security guards?
Not automatically. Many community credit unions operate safely with unarmed officers and strong duress-alarm protocols. Armed guards become appropriate when a credit union holds large on-site cash reserves, sits in a high-crime area, or faces long law enforcement response times.
What license does a bank security guard need in Texas?
Under Chapter 1702 of the Texas Occupations Code, unarmed guards need a Texas DPS Level II registration and armed guards need a Level III commission. The guard’s employer must also hold an active Class B or Class C license from the Texas DPS Private Security Bureau.
Key Takeaways
- Armed bank security guards provide strong psychological deterrence against armed robbery syndicates and secure high-risk cash transit windows.
- Unarmed officers offer an approachable presence for wealth management and community banking while effectively managing low-level disruptions.
- Armed deployments require strict firearm retention protocols, Level III retention holsters, and ongoing shoot/don’t-shoot training to mitigate crossfire liabilities.
- Branch decisions must weigh local crime rates, on-site cash volumes, physical layouts, police response times, and customer demographics under Bank Protection Act rules.
- In Texas, armed guards must hold an active Texas DPS Level III Commissioned Security Officer license backed by verified Class B or Class C contractor credentials.